Value Pick – October 4, 2026
Value Pick of the Week
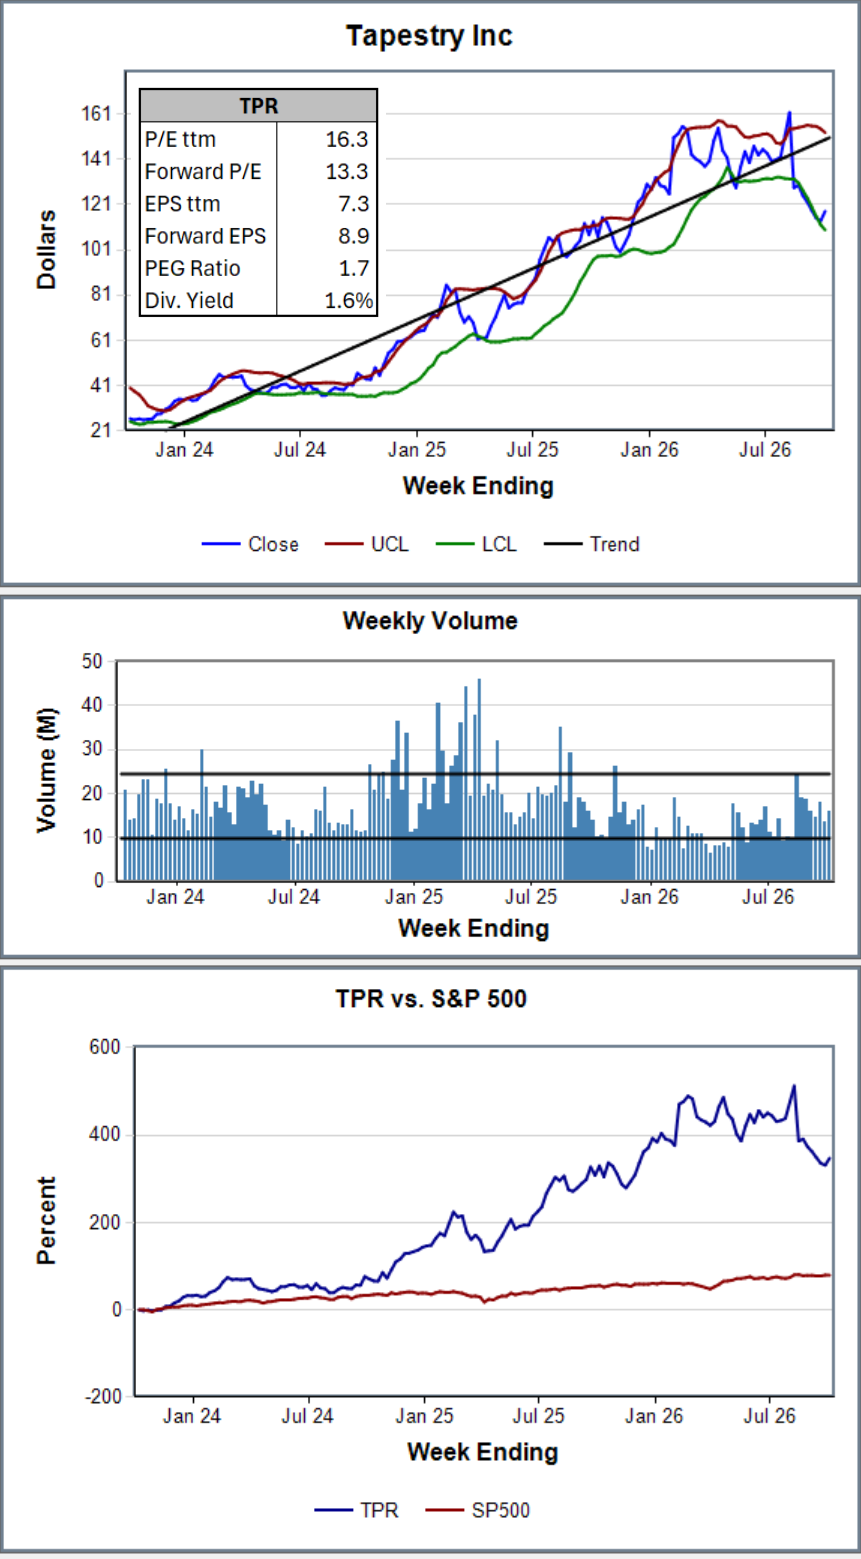
This week’s Value Pick is Tapestry (TPR), whose 3.7% gain this week suggests the turnaround is likely real. As mentioned last week, Tapestry is the upscale producer of the Coach and Kate Spade brands, with Coach providing most of the revenue and profits.
- Valuation reset: down ~27% from the 8/10 close of $162.36 while estimates rose. The current P/E stands at a low 16.3.
- Conservative guidance: Tapestry hit its three-year Investor Day targets two years early. It beat consensus every quarter of FY26, by 4–27%. FY27 guidance of $7.80–$7.90 resets to the long-term formula, leaving room to beat.
- Coach momentum: Q4 revenue +14% in constant currency, with Greater China +30%, Europe +25%, and North America +10%. Added ~9M new customers in FY26. Plans 40–50 net new doors in FY27, ~75% outside North America. Management sees a path to a $10B brand.
- Shareholder-friendly plans: a $1.35B buyback retires ~5.7% of shares at current prices. Dividend raised 16% to $1.85, a ~1.6% yield.
- Kate Spade already written off: FY27 assumes a high-single-digit decline and a modest operating loss. Stabilization or a sale would add value.
- Key risks: Coach is ~89% of revenue. A weak U.S. consumer and further tariff escalation are the main threats. Bear case is ~$95, at $7.30 EPS × 13x.
Market Summary
The S&P 500 fell 0.3% for the week ending October 2 — losing 0.3% over the weekend and then roughly flat across a U-shaped week.
- Oil re-escalated immediately. Trump rejected an Iranian peace proposal Monday — “They want to make a deal, but it is not the deal that I want to make” — and WTI jumped 4.22% to $96.31 with Brent +4.02% to $108.50 on renewed Strait of Hormuz risk.
- Friday reframed the cycle. September payrolls came in at +29,000 against +90,000 expected, and unemployment ticked up to 4.2% — bad news is good news, given the potential impact on future rate hikes.
How Our Picks Fared
Our past picks gained 3.4% against the S&P 500. Only Lam Research (LRCX) gained more than 10%, but other past picks had a solid week:
- ON Semiconductor (ON) rounded up to 10.0% but didn’t quite clear the bar
- ASML Holding (ASML) up 7.1%
- CrowdStrike (CRWD) up 7.1% (three-time pick)
📈 Lam Research (LRCX) rose 10.2%
- The driver was Micron Technology (MU) reporting fiscal Q4 on September 30. For a wafer-fab-equipment supplier, a memory maker’s capex guide is the order book, and this one was the number that mattered.
- Micron’s first-half fiscal 2027 capex guided to approximately $25 billion, with higher spending expected in the second half. Micron’s entire FY2026 capex was $27.37 billion.
- The move accumulated rather than gapped. LRCX advanced in roughly 3% increments across at least three sessions — 9/29 to 10/2. That’s different from the CRWD move, which was a single-day repricing. A multi-day grind on a capex guide reads more like institutional accumulation than a headline reaction.
Past Picks Review — Shipping & Logistics
Three recommendations, two companies. CSX has averaged 18.4% per year and, combining the two recommendations, ODFL has gained 8.0% per year — reasonable gains, but they haven’t beaten the benchmark. All three recommendations are trailing the S&P 500 badly.
Old Dominion Freight Line (ODFL) — HOLD, with triggers
- The pricing power is mostly fuel, not price. Q2 LTL revenue per hundredweight rose 15.2% to $37.84 — but fuel surcharges accounted for roughly 9.7% of the gain. Management guided Q3 ex-fuel yield down to 4%–4.5%.
- Volumes are still contracting in year three of the downturn. Tons per day fell 4.1% and shipments per day 5.7% in Q2. Record revenue of $1.554 billion, up 10.4%, was produced on less freight — the growth is a fuel-and-rate artifact, not demand.
- Oil prices are projected to fall below $80 a barrel. If crude returns to $70–80, the 9.7% surcharge contribution evaporates. Against declining volumes and core pricing decelerating toward 4%, the revenue line turns negative.
- The trend is improving, and that’s the bull case. Tons went from −7.7% in the first quarter to −4.1% in the second, weight per shipment turned positive at +1.7%, and the operating ratio held at 70.1% — a figure no other LTL carrier approaches. The operating leverage on a network that good is substantial if volumes turn.
CSX Corp (CSX) — HOLD, with triggers
- The business is executing, and the turnaround is real. Second-quarter revenue hit a record $3.94 billion, up 10%, with earnings per share up 23%, operating income up 17%, and operating margin expanding 240 basis points to 38.3%. Volume rose 6% with growth across all three segments.
- Growth is volume-driven, not price-driven — the opposite of ODFL. Intermodal volume rose 9% with revenue up 26%, which management credited directly to truck-to-rail conversions. Merchandise volume rose 4% on chemicals and minerals. Coal volume rose 4% on export shipments following mine restarts. Three working engines, only one of which depends on the truckload squeeze.
- Management raised full-year guidance to mid-to-high-single-digit revenue growth, operating margin expansion above 350 basis points, and free cash flow growth above 80%, with early third-quarter units running roughly 6.5% higher year over year.
- Analyst dispersion is wide and skewed down. Across 23 analysts the range runs $32 to $60 — from −32.5% to +26.5%. The bear tail is larger than the bull tail.
- Lower oil prices favor trucks. A railcar holds roughly five truckloads of freight; LTL carriers like ODFL don’t get higher volume when freight moves from rail to trucks — both CSX and ODFL will be hurt as oil prices fall.
The Triggers
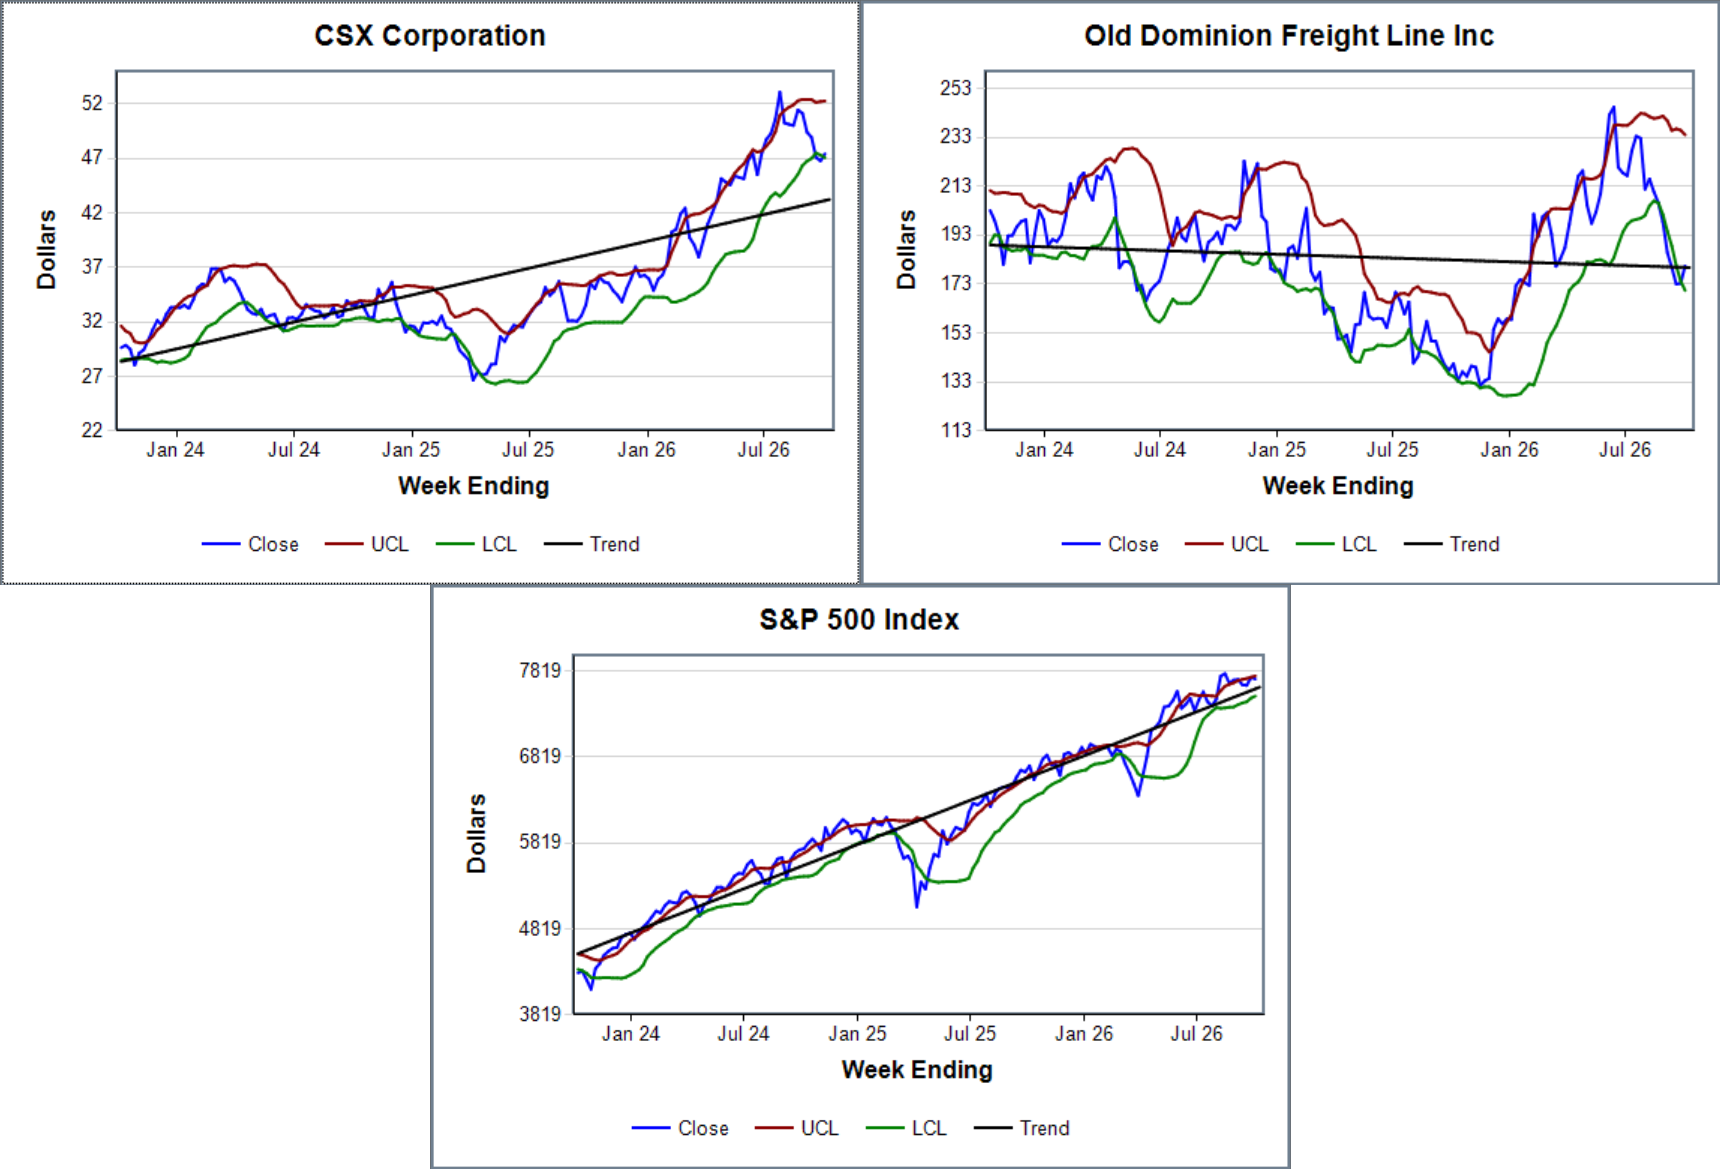
Both companies are near their recent lows while the S&P 500 is within 100 points of the all-time high, and both are in the midst of a turnaround, having crossed above the Lower Statistical Control Limit (LCL) during the past week. Oil prices are unlikely to drop significantly until at least late November, so we don’t want to miss the turnaround.
When we’ll sell:
- The companies approach their respective Upper Control Limits (UCL)
- A miss relative to the corporate guidance
- A sustained reduction in oil prices validating the primary sell thesis
Have a great week!