Value Pick – October 11, 2026
Value Pick of the Week
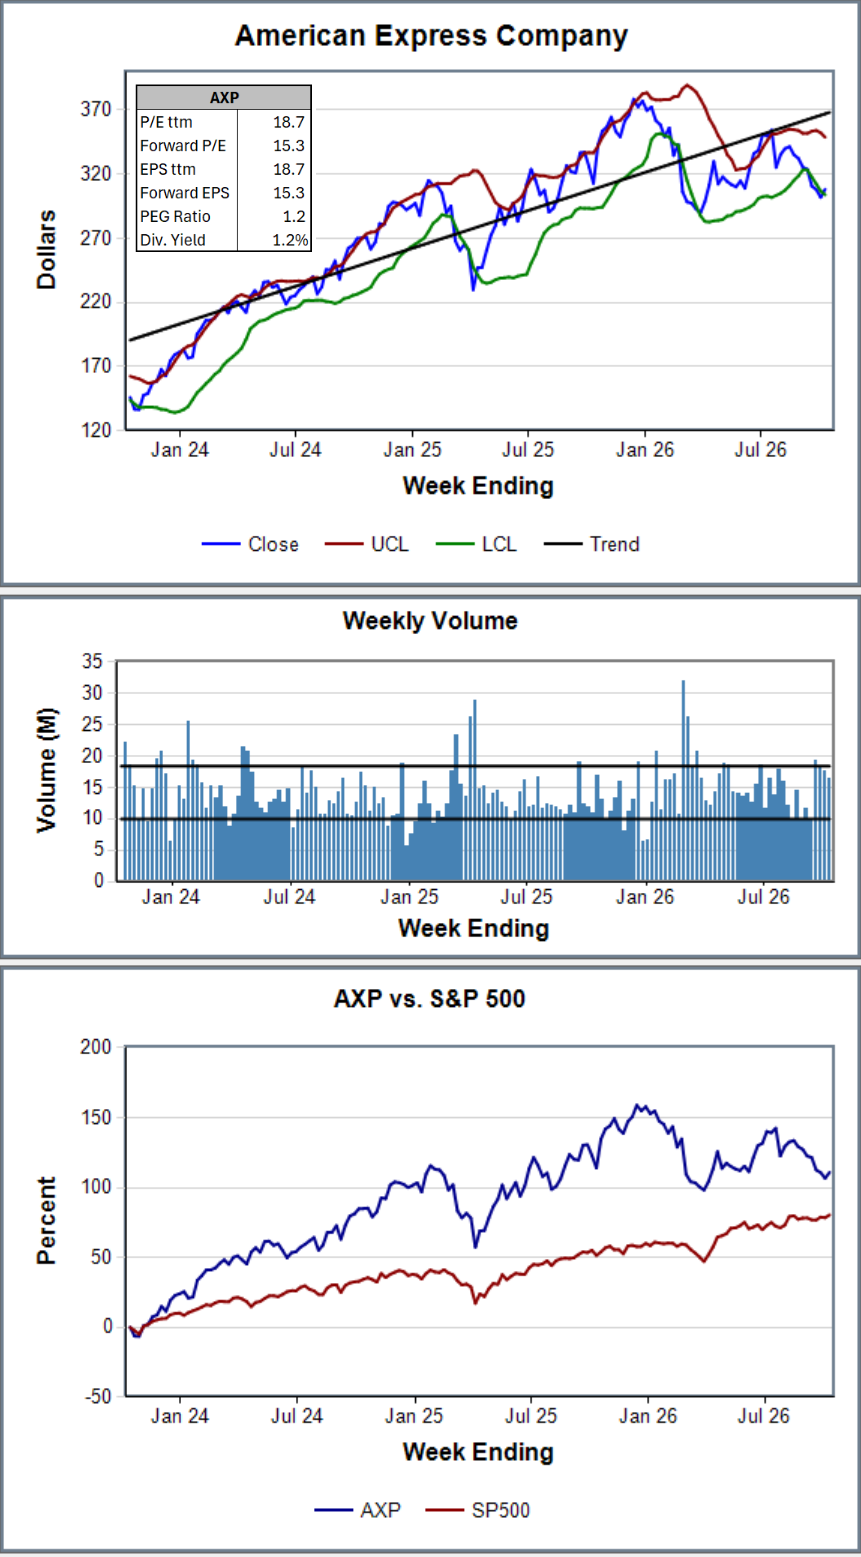
This week’s Value Pick is American Express (AXP). We first recommended AXP in September 2023, and again in March 2025. The 2023 pick up 91.0% and beating the S&P 500 by 15.5%, the 2025 pick is up 17.4% but lagging the S&P by 22.6% ─ I think it’s ready for another run. American Express is a premium payments and lending franchise with a powerful combination of brand strength, affluent customers, recurring fee revenue, and opportunities for continued earnings growth. Its competitive advantage goes beyond the American Express card itself: the company has built an integrated ecosystem connecting cardholders, merchants, rewards, travel services, and financial products. That ecosystem encourages customers to spend more, gives merchants access to desirable customers, and creates multiple revenue streams for American Express.
- A differentiated, affluent customer base — American Express has historically attracted customers who spend more than the average credit card user, particularly on travel, dining, entertainment, and other discretionary purchases.
- A business model with multiple growth engines:
- Merchant discount revenue: earned when cardholders make purchases at participating merchants.
- Card fees: recurring annual fees, particularly from premium products such as the Platinum Card.
- Net interest income: revenue generated from lending to cardholders, net of interest expense.
- Other revenue: services, travel-related activities, and network partnerships.
- A valuable network with room to expand — American Express operates a differentiated network that combines card issuance, customer relationships, and merchant acceptance.
What could make the bull case wrong?
- Consumer weakness
- Premium-card competition
- Credit risk
Market Summary
The NASDAQ had a record close on Monday, and after setting a new intraday high of 7,844.22 on Tuesday, the S&P finished the week at 7,811.54, up 1.2%.
- The AI trade cracked. A report that OpenAI’s annualized revenue was running roughly $20 billion below projections hit technology hardest — read as softness on the inference side, which is the part that translates into hardware demand. Semiconductors sold off, with higher oil prices compounding it.
- Consumer sentiment fell again. Preliminary October University of Michigan consumer sentiment fell to 46.3 — below the 47.8 consensus and September’s 48.1 final — the third consecutive decline.
- Breadth stayed narrow. Small caps lagged for the fifth straight week, a lack of breadth in a market where the major indexes (S&P, NASDAQ, and Dow) were near record highs.
How Our Picks Fared
Our past picks lost 2.7% to the benchmark S&P 500. In addition to our two companies that fell more than 10% (below), ON Semiconductor (ON) and Lam Research (LRCX) lost 8.7% and 8.2%, respectively. Both were caught in the ripple effect from the Anthropic revenue report.
📈 Zscaler (ZS) rose 18.9%
This one is a head-scratcher — Zscaler’s investor day had the same kind of news as ON Semiconductor, but ZS was rewarded with an 18.9% gain while ON lost 8.7%. The near-term numbers ZS management reaffirmed were not good:
- FY2027 revenue growth guided to 16.6%–17.5%, ARR growth 16.6%–17.4% — a deceleration from roughly 25%.
- A restructuring cutting about 3% of global headcount, with $30–33 million in severance charges.
- Chief Revenue Officer Mike Rich departed effective October 1, filed on an 8-K.
The difference between the ZS and ON events: analysts were grading whether the long-term story is believable and whether the event removes uncertainty or adds it. ON added a five-year wait; Zscaler removed a sales-execution worry.
📉 Amkor Technology (AMKR) fell 12.3%
- I found no company-specific catalyst inside the window. Amkor’s Q3 earnings are scheduled for October 26.
- What hit it was Thursday’s AI de-rating starting with Anthropic — the Philadelphia Semiconductor Index fell 3.4% Thursday. Names dependent on lab customers fell hardest, and Amkor sits one layer behind them.
📉 IES Holdings (IESC) fell 12.3%
That’s not a typo — both IESC and AMKR fell by the same amount to the second decimal point.
- Like AMKR, there was no company-specific catalyst for the drop that I could find — IESC’s last report was on July 31 and they beat on revenue and EPS.
- The most likely reasons for the drop: IESC is an electrical contractor whose growth story is data center build-out, and it has a history of volatility.
- San Francisco and Oakland put a moratorium on data center permits, a six-month pause in Raleigh, and a statewide pause in New York — with San Francisco’s rule also pausing permits to expand existing facilities. That hits the forward project pipeline a contractor like IESC bids into, rather than current demand, although I couldn’t find anything that led me to believe IESC has contracts in any of those markets.
Past Picks Review
No review this week — Aerospace & Defense next week.
Have a great week!